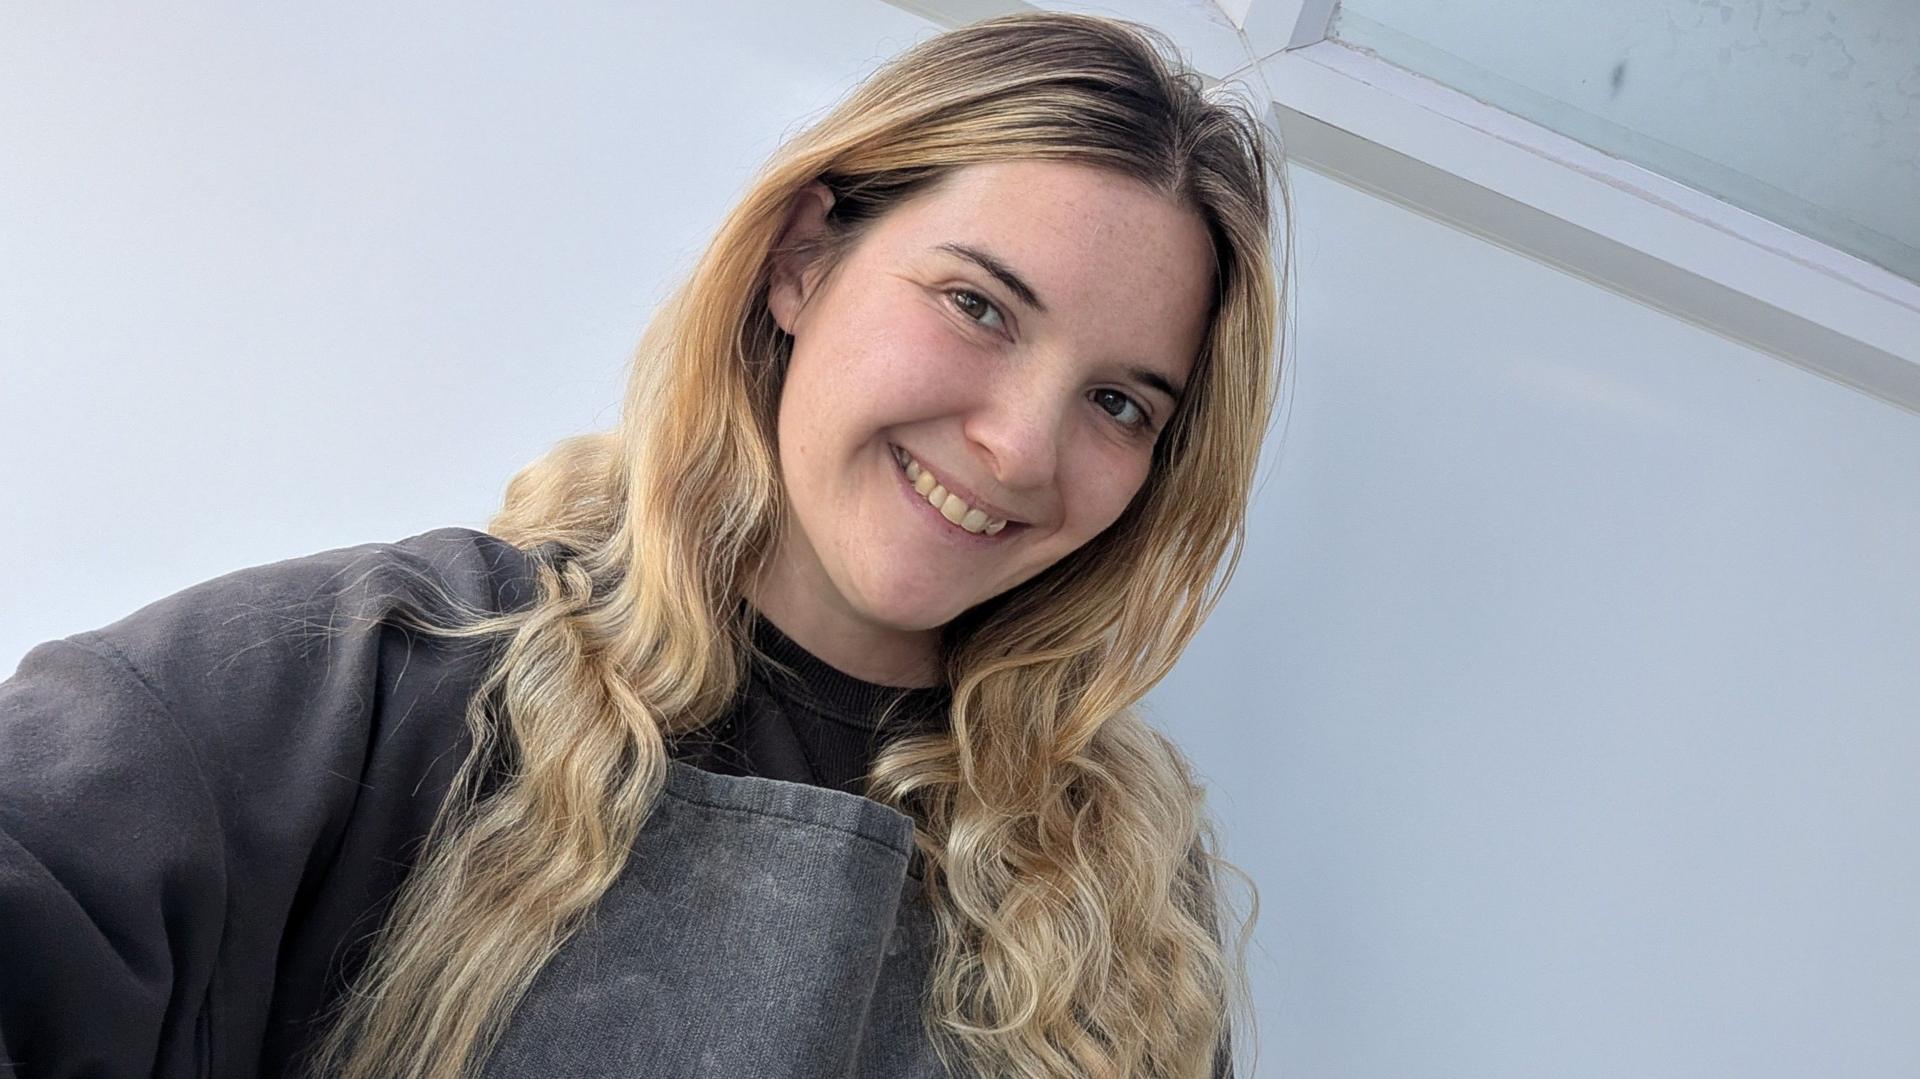
Sophie Hope's mortgage application was denied after her credit score plummeted from excellent to very poor, the result of identity fraud she did not discover until applying for the loan. Someone had opened accounts in her name at catalogue sites and ordered items including a PlayStation 4 and Nike socks, then transferred the resulting debt to a secondary finance company where it accumulated for three to four years.
Her case illustrates a broader debate about whether credit scores, produced in the UK by Experian, Equifax and TransUnion, adequately assess lending risk. Consumer finance lawyer Funmi Olufunwa argues that "a credit score is backward looking. It's looking at what has happened in the past, which doesn't necessarily predict what actually is affordable." Credit scores also disadvantage thin-file applicants such as young people and recent immigrants who lack credit history.
AI-powered lending firms Upstart and Zest AI have built businesses offering lenders alternatives to traditional scoring. Upstart states its machine-learning models examine more than 2,500 variables and "can make significantly more loans at low prices to borrowers from every demographic group." Mortgage expert Sarah Tucker says AI could help lenders analyse broader information sets and "build a more individual picture of someone's affordability and risk," potentially improving financial inclusion.
Concerns remain. Sandra Wachter, professor of Technology and Regulation at Oxford University, warns that AI "does not know about existing social inequalities that impact decisions and could just replicate what it has seen in the past." She argues that real transformation requires accountability alongside automation and that firms must apply existing regulations and establish guardrails to prevent AI from perpetuating past biases.
Evangeline Atkinson founded Noggin HQ, a credit reference agency authorised by the FCA in June, after being denied a phone contract despite paying rent and bills for years because she had no credit record with the big three agencies. Noggin HQ analyzes current account transactional data without using AI, which Atkinson warns "carries the risk of inbuilt bias" when processing sensitive data about protected characteristics.
The big three credit scoring firms have begun experimenting with AI. Experian announced a partnership with OpenAI in August 2026 allowing users to check credit scores inside ChatGPT. Equifax launched Equifax Amplify AI, which it says uses machine learning.